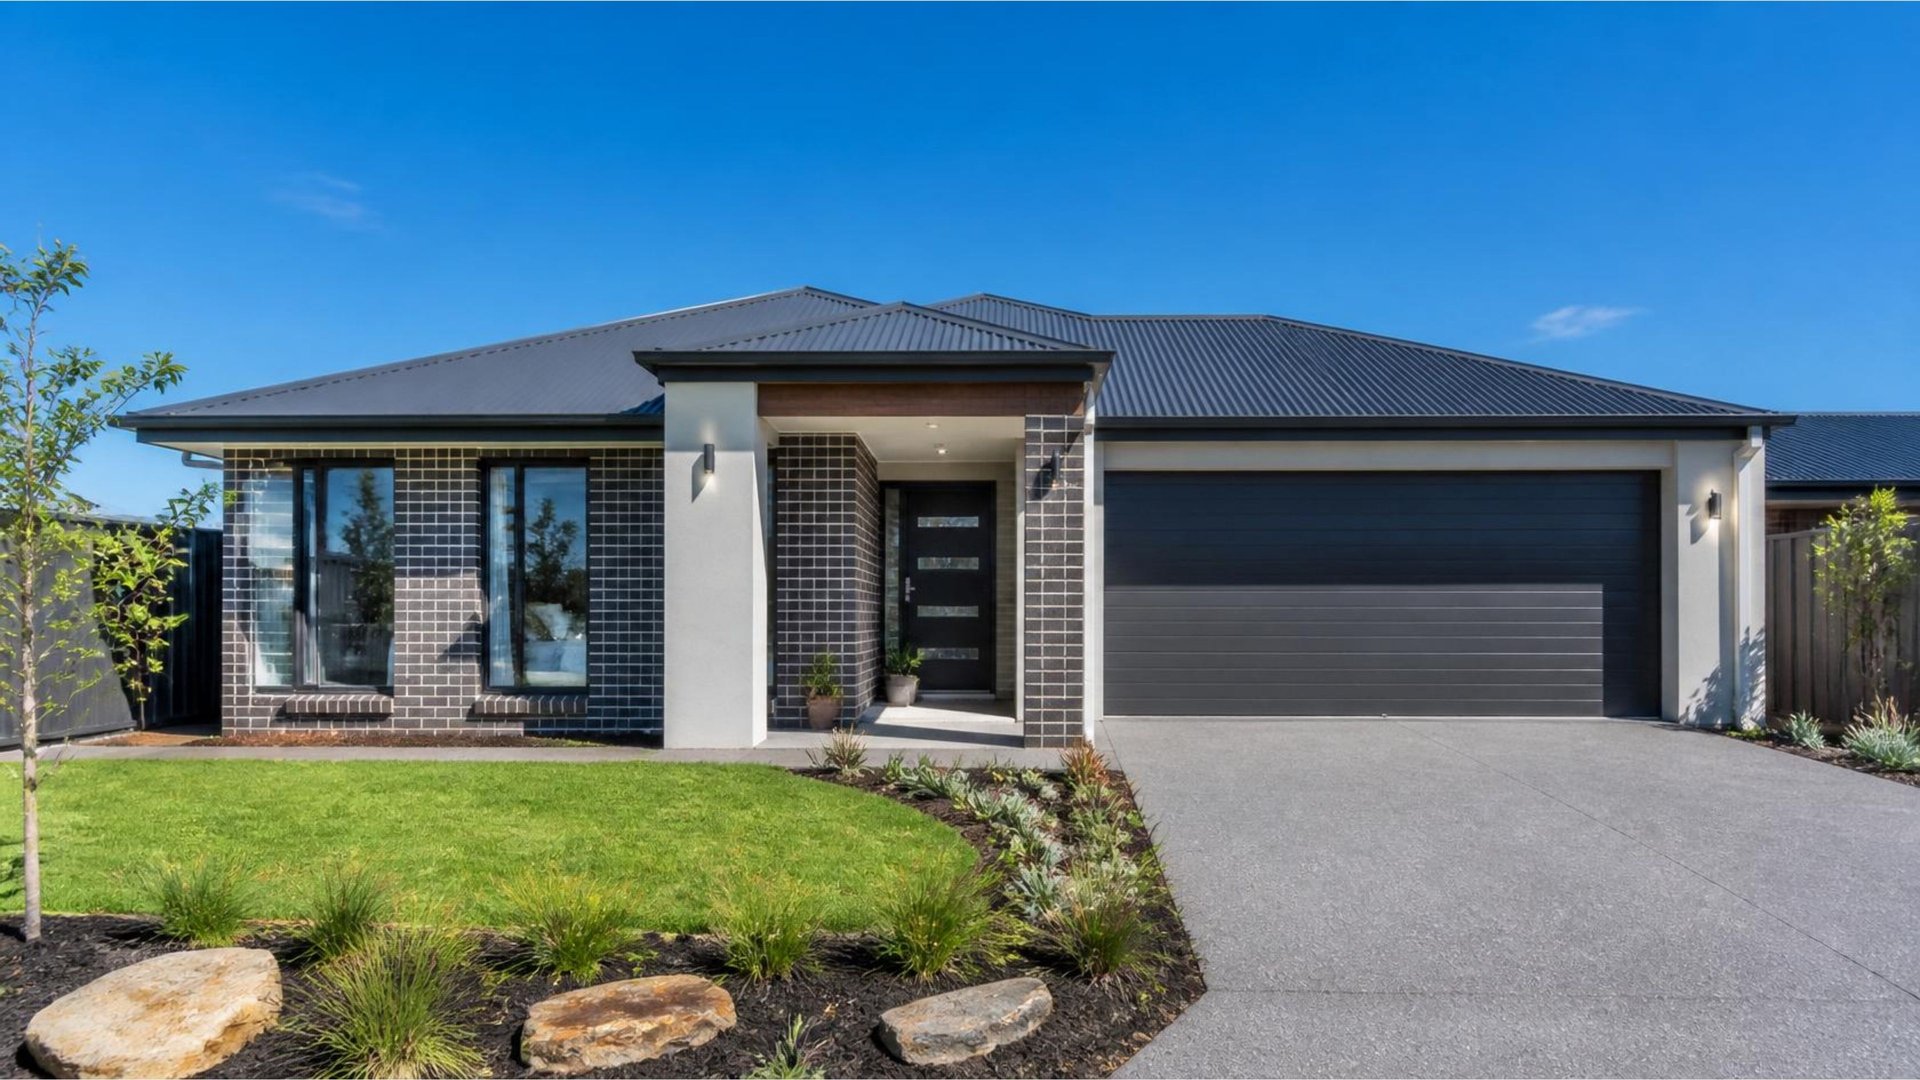
Two rental properties can look almost identical on paper — same suburb, same rent, same
price — and still produce very different tax outcomes. More often than not, the
difference comes down to one thing: depreciation. It's the least glamorous
part of property investing and one of the most valuable, and it's the single biggest reason a
new build tends to be more tax-effective than an established home.
Two kinds of depreciation
The tax rules let you claim the gradual wear-and-tear on an income-producing building in two
separate buckets. Division 43 (capital works) covers the structure itself
— the bricks, concrete, roofing and permanently fixed items. For residential buildings
constructed after 15 September 1987, it's generally deductible at 2.5% a year over 40
years. Division 40 (plant and equipment) covers the removable,
mechanical assets — the oven, dishwasher, carpets, blinds, air-conditioning and hot
water system. These are written off over their individual effective lives, and because many
are short-lived, the deductions are front-loaded into the early years when
your cash flow needs them most.
The 2017 rule that changed the game
Here's the pivot point. Since 9 May 2017, investors who buy a
second-hand residential property can no longer claim Division 40 depreciation
on the previously-used plant and equipment that comes with it. You still get the Division 43
capital-works deductions on the structure, but the write-offs on the existing oven, carpets
and air-conditioner are gone.
The exception — and it's a big one — is new (or substantially renovated)
property. When you're the first investor to own a brand-new home, every one of those
plant-and-equipment assets is new, so you can claim the full Division 40 deductions on top of
the capital works. That single rule is why the numbers diverge so sharply between new and
established.
“With a new build you claim both buckets — the structure and
the fittings. With most established homes, one of them is simply off the table.”
A brand-new investment property hands you both Division 43 and Division 40
— and the plant-and-equipment portion is largest in the first few years. A comparable
established home usually gives you the capital-works claim only. As an illustration, a new
build might generate first-year depreciation in the order of
$12,000–$15,000,
where a similar established property might produce a fraction of that. The exact figures
depend entirely on the building, so the number that matters is the one on a quantity
surveyor's schedule prepared for your specific property — not a rule of thumb.
Why a non-cash deduction is so useful
Depreciation is a non-cash deduction — you're not writing a cheque to
claim it. It reduces your taxable income, which lifts your after-tax cash flow, and that extra
cash flow is exactly what a disciplined plan puts to work. Redirected against the
non-deductible loan on your own home, those tax savings can shorten your
mortgage by years. That's the connection we care about most: depreciation isn't about a
bigger refund for its own sake, it's fuel for paying down debt faster and freeing up your
future.
And now the Budget stacks on top
The 2026–27 Federal Budget added a second reason new builds stand out. From
1 July 2027, negative gearing on established homes is being wound back and
the 50% CGT discount is changing — but new builds are exempt, keeping
negative gearing and a choice of CGT method. So a new build no longer just offers the bigger
depreciation deductions; it also holds onto the tax advantages that established properties are
losing. The benefits compound.
Do it properly
Two steps make the difference. First, have a qualified quantity surveyor
prepare a depreciation schedule — its cost is itself deductible and it typically pays
for itself many times over. Second, make sure the property was the right choice in the first
place. A generous depreciation schedule on a poorly-chosen property is still a poorly-chosen
property. That's where getting the structure right up front earns its keep.
Capital works (Div 43) covers the structure at 2.5% a year for 40 years.
Plant & equipment (Div 40) covers fittings, front-loaded into early years.
Since May 2017, second-hand homes lose the plant & equipment claim.
New builds keep both — and, from 2027, keep negative gearing too.
Get a quantity surveyor's schedule for the real numbers.
This article is general information only and doesn't take your personal circumstances
into account. Depreciation outcomes vary by property; example figures are illustrative.
Please seek advice from a registered tax agent and a quantity surveyor before acting.
 Mortgage
 Retirement
 Process