What the Federal Budget means for property investors
The 2026–27 Federal Budget, handed down on 12 May 2026, put housing squarely in the
spotlight — and delivered the biggest change to how property investors are taxed in a
generation. If your plan is to pay down debt faster and build a comfortable retirement, the
new settings are worth understanding, because they reward a very particular, disciplined
approach. Here's a plain-English look at what's changed, who it affects, and what it means
for the way you invest.
The two big changes
From 1 July 2027, two long-standing tax settings are being reshaped. First,
negative gearing on established homes is being wound back: for an established
residential property bought after 7:30pm on 12 May 2026, rental losses will no longer be
deductible against your wages or other income. Instead, those losses can only be offset
against income from residential property (or a future capital gain on residential property),
with any excess carried forward to later years.
Second, the capital gains tax (CGT) discount is changing. The familiar 50%
discount for assets held longer than a year is being replaced with a combination of
cost-base indexation (so your purchase cost is lifted by inflation before
the gain is worked out) and a 30% minimum tax rate on net capital gains.
These CGT changes apply only to gains that accrue after 1 July 2027, so growth you've already
banked keeps the old treatment. The family home stays fully exempt, and pensioners and
income-support recipients are excluded from the 30% minimum rate.
If you already own, you're grandfathered
This is the reassuring part. Any investment property you owned at 7:30pm on 12 May 2026
— including one already under contract and awaiting settlement — is
grandfathered. You keep negative gearing on that property under the current
rules for as long as you hold it, and the 50% discount still applies to the growth that
accrued up to 1 July 2027. In other words, the changes are prospective: they're about
shaping future decisions, not clawing back what you've already built.
“The Budget didn't close the door on property investing — it
pointed it firmly towards new housing supply.”
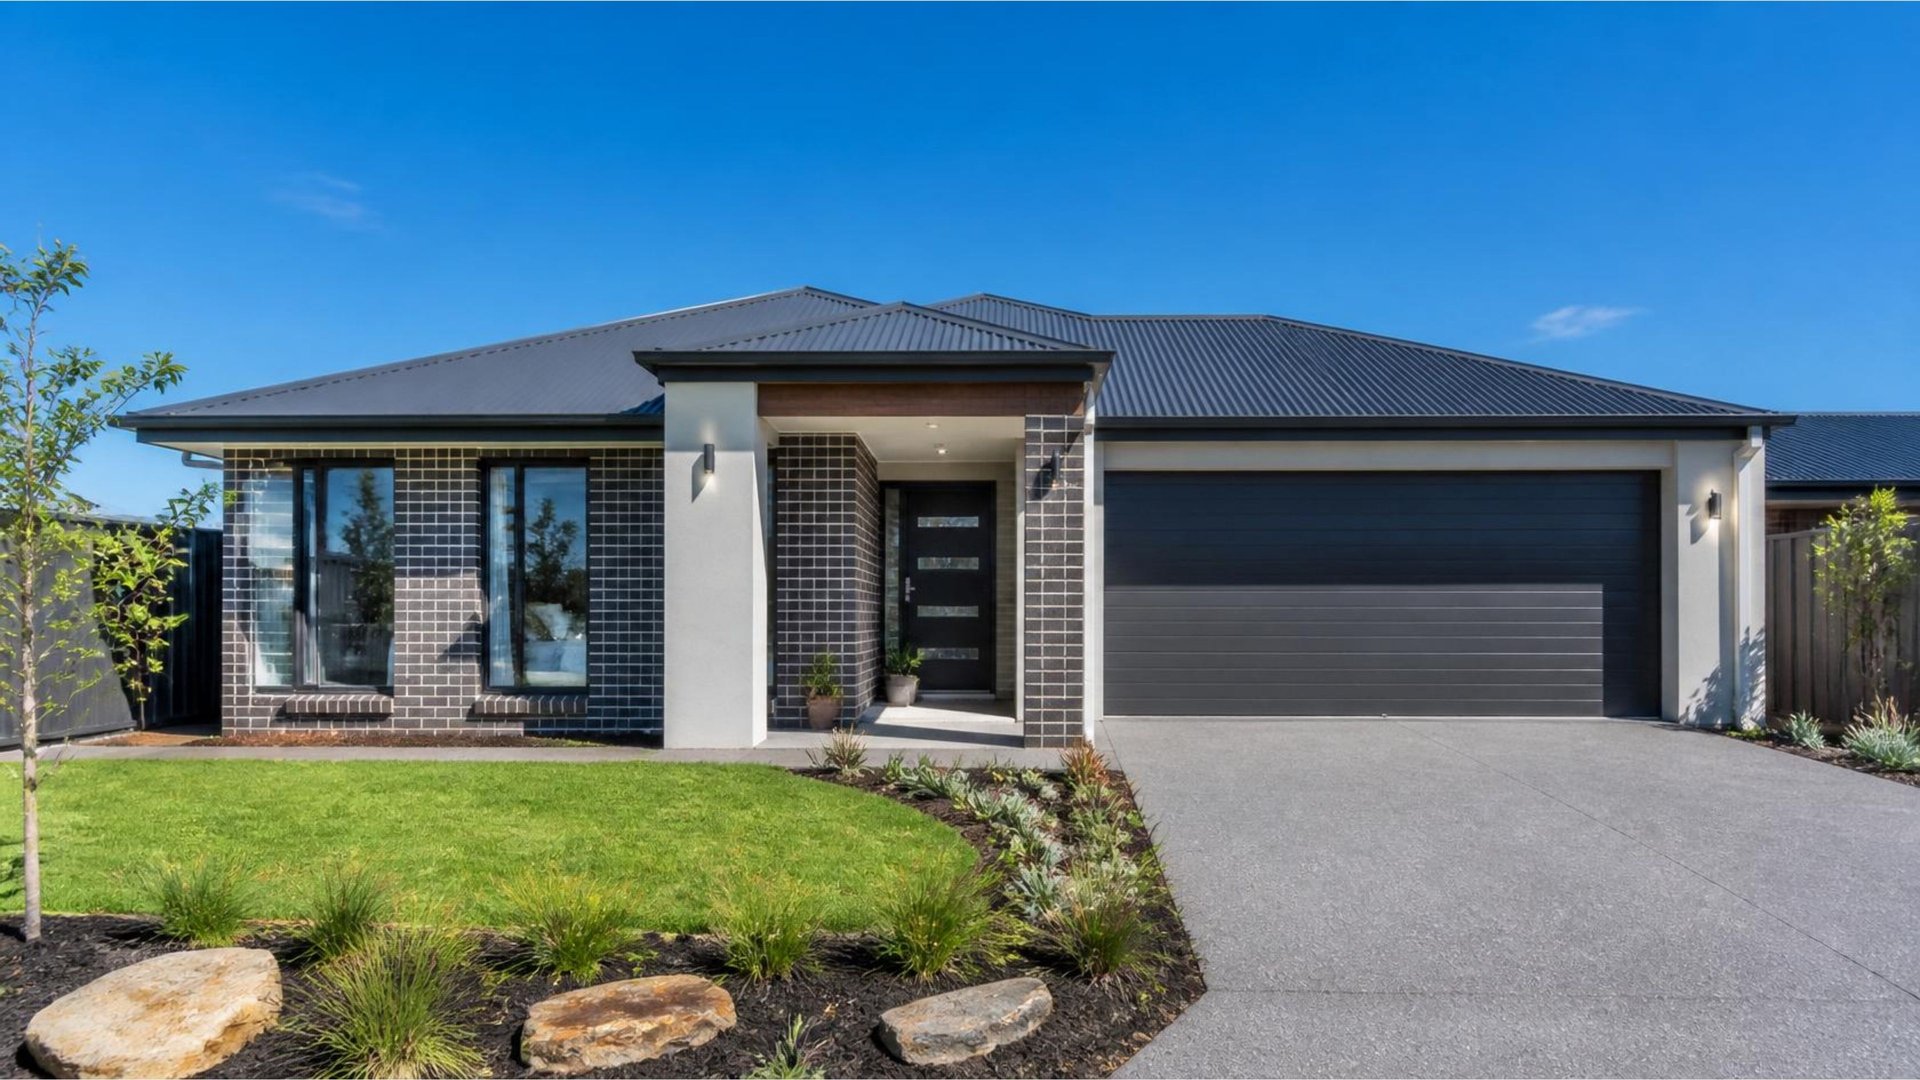
The clearest signal in the Budget is the carve-out for new builds. Newly
built homes are exempt from the negative gearing wind-back, and investors in a new build can
still choose between the existing 50% CGT discount and the new indexation
method — whichever leaves them better off. A "new build" broadly means a home that adds
to housing supply: an apartment bought off-the-plan, a house built on vacant land, or a
knock-down rebuild that replaces one dwelling with more (say, a single house replaced by a
duplex). The property generally needs to be sold or first tenanted while still new, and the
concessions attach to the first investor — a later buyer of that same home doesn't
inherit them.
None of this is accidental. The Government's stated aim is to steer investment away from
competing for existing homes and towards creating new ones, easing supply
pressure over time. For an investor, it means the tax system now leans in the same direction
that a well-built new-property strategy has always pointed.
The bigger picture: supply, foreign buyers and tax cuts
Alongside the headline reforms, the Budget backed supply directly — including
around $2 billion for the councils and
utilities that unlock new housing (roads, water, power), as part of a broader federal housing
commitment. The ban on foreign buyers purchasing established homes was extended to
30 June 2029, and personal income tax rates are being trimmed in stages
(with the second-lowest rate stepping down toward 14%), plus modest measures like a standing
work-related deduction. Individually small; together, they nudge more households toward home
ownership and shift the balance of new investment toward fresh supply.
What it means if your goal is debt reduction and retirement
A word of caution first: tax should never be the reason you buy a property. The tax tail
shouldn't wag the investment dog, and a deduction is only ever worth having if the underlying
decision is sound. That said, the new rules genuinely reward the approach we've always
favoured — using a quality new-build investment, structured carefully, to accelerate
debt reduction on your own home and build an income stream for retirement, rather than
speculating on established stock for a tax break that's now being withdrawn.
If you already hold investments, the practical message is: don't panic, and don't rush to
sell — your grandfathered position is valuable. If you're weighing up your next move,
the settings now make it more important than ever to get the structure and the property type
right from the outset. That's exactly the kind of modelling we do with clients: mapping how a
decision plays out across debt, cash flow, tax and your retirement timeline — before
you commit.
Changes start 1 July 2027 — property you already own is grandfathered.
Negative gearing on established homes is being limited to residential income only.
The 50% CGT discount is replaced by indexation plus a 30% minimum rate on future gains.
New builds keep negative gearing and a choice of CGT method.
The family home and super are unaffected.
This article is general information only, current as at May 2026, and doesn't take your
personal circumstances into account. Tax and Budget measures can change as legislation is
finalised — please confirm the current detail and seek personal advice before acting.
 Mortgage
 Retirement
 Process